Nike stock is back under pressure after the athletic-wear giant reported disappointing fiscal 2027 first-quarter revenue and issued a much weaker full-year outlook.
The central issue is no longer simply whether Nike can reduce costs. Investors are watching whether the company can restore product demand, rebuild its position in China, strengthen the Jordan and Sportswear businesses, and return to sustainable revenue growth.
Nike reported $11.2 billion in fiscal Q1 2027 revenue, down 4% year over year on a reported basis and 5% on a currency-neutral basis. Gross margin improved to 42.8%, while diluted EPS came in at $0.48. However, management now expects fiscal 2027 revenue to decline by a high-single-digit percentage.
The company is also introducing a new operating-model transformation called Pace, which Nike expects to generate approximately $2.5 billion in cumulative savings through fiscal 2031.
For investors following the latest nike stock updates, the important question is therefore not just where the share price goes next. It is whether Nike’s underlying business can eventually produce the growth and profitability that supported its previous valuation.
Nike Stock: Key Stats and Performance
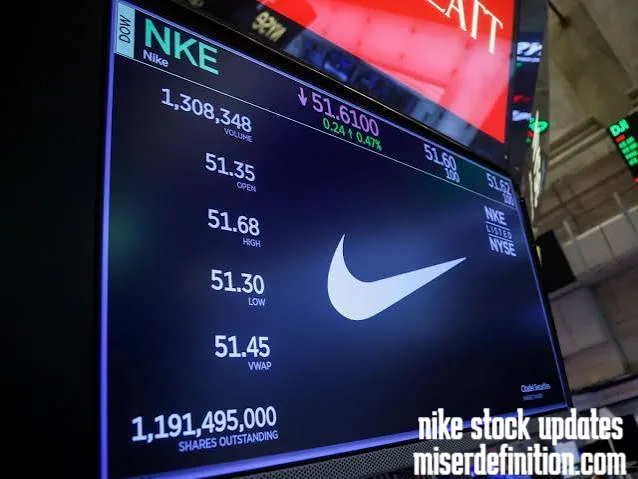
Nike trades on the New York Stock Exchange under the ticker NKE.
As of October 2, 2026, available market data showed Nike shares around $33.02, following a 6.06% decline during the October 2 session. The previous day’s close was $35.15.
At roughly $33 per share, 500 Nike shares would have a market value of approximately $16,510, before commissions, taxes or other transaction costs.
Nike’s shares have experienced a dramatic decline from their previous highs. The stock’s 52-week range reported around the October 2 session was approximately $31.97 to $74.78.
The decline reflects more than temporary market volatility. Investors have been reassessing Nike’s growth prospects as revenue growth has weakened, competition has intensified and management has undertaken increasingly significant restructuring.
What Happened to Nike Stock?
Nike stock has fallen because investors are increasingly concerned that the company’s turnaround will require more time, lower near-term revenue and heavier restructuring than previously expected.
The latest earnings report reinforced that concern.
Nike’s fiscal Q1 2027 revenue fell 4% to approximately $11.2 billion. More importantly, management’s fiscal-year guidance calls for revenue to decline by high single digits.
That means Nike expects another difficult year even while its turnaround program is being implemented.
The market reaction was significant because investors generally value companies based on expected future earnings rather than simply their current balance sheets.
Nike can reduce expenses, but cost reductions alone cannot create sustainable growth. The company ultimately needs consumers to buy more Nike products at healthier prices.
Why Did Nike Stock Fall?
There are several interconnected reasons.
1. Weak fiscal 2027 revenue guidance
Nike expects fiscal 2027 revenue to decline by a high-single-digit percentage.
That is a substantial deterioration from what investors would normally expect from a mature global consumer brand with Nike’s scale.
Management also expects adjusted diluted EPS of $1.15 to $1.35, excluding approximately $0.15 of restructuring expenses associated with Pace.
2. Greater China remains a major problem
Nike’s Greater China revenue fell 26% in fiscal Q1 2027 to approximately $1.18 billion.
The decline affected both wholesale and direct sales.
Nike said it is deliberately cleaning up its Chinese digital distribution network, including reducing distribution through channels that do not fit its marketplace strategy.
That can improve pricing discipline and brand presentation over time, but it can also reduce sales in the short term.
3. Nike Sportswear and Jordan are under pressure
Nike’s performance-oriented categories are producing better results, but the broader lifestyle portfolio remains weaker.
Sportswear and Jordan are particularly important because they represent a major portion of Nike’s global business.
Management is deliberately reducing some supply in these categories, including certain retro products, as it tries to restore product scarcity, improve inventory health and strengthen the brand’s premium positioning.
4. Investors expected a faster turnaround
CEO Elliott Hill returned to Nike with a strategy centered on sport, product innovation and operational discipline.
The latest results suggest that rebuilding the business will take longer than some investors initially hoped.
That difference between expectations and reality can have a major impact on Nike stock.
Nike’s Latest Earnings Results Explained
Nike’s fiscal Q1 2027 results contained both positive and negative signals.
| Metric | Fiscal Q1 2027 |
|---|---|
| Revenue | $11.2 billion |
| Revenue change | -4% reported |
| Currency-neutral revenue | -5% |
| Gross margin | 42.8% |
| Gross-margin change | +60 basis points |
| Diluted EPS | $0.48 |
| Net income | About $0.7 billion |
| Inventory | $7.8 billion |
| Cash and short-term investments | $8.4 billion |
The improvement in gross margin is important. Nike said lower warehousing and logistics costs helped increase gross margin by 60 basis points to 42.8%.
Selling and administrative expenses also declined 3% to $3.9 billion.
However, revenue remains the bigger issue.
Nike Brand revenue declined 4%, while Nike Direct revenue fell 8%. Nike Brand Digital declined 13%.
The company therefore has evidence of improving cost control without yet demonstrating a broad-based return to top-line growth.
What Does Nike’s Revenue Outlook Mean for Investors?
The immediate outlook is difficult.
Nike expects fiscal 2027 revenue to fall by a high-single-digit percentage, while adjusted EPS is expected to be between $1.15 and $1.35.
Management has also indicated that some corrective actions will create additional short-term pressure.
This distinction matters.
A falling revenue figure does not necessarily mean a turnaround strategy is failing. Management may intentionally reduce low-quality sales, excessive discounts or unproductive distribution.
But investors eventually need evidence that those sacrifices are producing healthier demand.
The key test will be whether Nike can eventually move from:
inventory cleanup → healthier distribution → stronger products → improved full-price sales → revenue growth → higher profitability.
Until that sequence becomes visible in the financial statements, the recovery case remains dependent on future execution.
Is Nike’s Turnaround Actually Working?
The answer is mixed.
Nike says its Sport Offense strategy is producing measurable progress across performance categories, including running, football, tennis and golf.
North American revenue also increased 2% in Q1, helped by performance categories.
That provides evidence that Nike’s brand and product capabilities have not disappeared.
At the same time, Sportswear, Jordan Brand and Greater China remain major weaknesses.
The company therefore has two different stories inside the same business.
The positive story: performance sports are showing momentum and margins are improving.
The negative story: the lifestyle portfolio, China business and overall revenue trajectory remain weak.
This makes Nike’s recovery prospects highly dependent on whether management can transfer momentum from performance categories into the broader portfolio.
What Is Nike’s New Restructuring Plan?
Nike calls its latest operating-model transformation Pace.
The plan builds on the company’s earlier cost-realignment efforts and includes:
- Streamlining the organization
- Reducing roles across Nike
- Reorganizing the company around three geographic structures
- Modernizing the global supply chain
- Establishing a new campus in India
- Redirecting investment toward product innovation and sport
- Improving operating productivity
- Repositioning Sportswear and Jordan
- Restructuring the Greater China business
Nike expects approximately $2.5 billion of cumulative savings through fiscal 2031.
However, the savings will not be free.
Nike expects approximately $1 billion of pre-tax charges through fiscal 2031, primarily related to employee and restructuring costs, in addition to approximately $300 million of severance costs recognized in fiscal 2026.
The company expects approximately $300 million of those additional charges in fiscal 2027.
Nike has also said that decisions involving affected roles will begin in calendar 2027 and beyond.
For investors, the key distinction is between cost savings and profitable growth.
Cost savings can improve margins, but long-term shareholder value ultimately depends on Nike producing stronger products and generating healthier demand.
Why Is Nike Struggling in China?
Nike’s China problem is broader than one weak quarter.
Greater China revenue has fallen sharply, while local and international competitors have become more competitive.
Chinese consumers have more alternatives from companies such as Anta Sports, Li-Ning and Xtep, while international competitors such as Adidas and other specialist sportswear brands are also competing for consumers.
Nike’s own strategy recognizes that its Chinese digital marketplace needs to be simplified.
The company plans to concentrate its digital presence around official Nike flagship storefronts on platforms including Tmall, JD and Douyin, alongside Nike.com and the Nike app.
Nike says the objective is to reduce deep discounting, improve product presentation and create a more consistent consumer experience.
The challenge is that this cleanup is expected to hurt revenue and profitability in the near term.
That creates an unusual situation for Nike stock: a declining China revenue figure could partly reflect deliberate restructuring rather than purely declining consumer interest.
Investors therefore need to examine what happens after the cleanup rather than looking at one quarter in isolation.
Nike vs. Adidas and Chinese Competitors
Competition is one of the biggest variables in the Nike investment outlook.
Adidas provides an important comparison. Its 2025 Greater China brand sales increased 13% on a currency-neutral basis, reaching €3.623 billion in reported net sales. Adidas attributed the performance to growth in both Lifestyle and Performance categories.
That does not mean Adidas has solved the Chinese sportswear market or that Nike cannot recover.
It does demonstrate that consumer demand exists in the market and that competitors are capable of gaining momentum.
Chinese brands such as Anta, Li-Ning and Xtep also compete with Nike through localized products, pricing and consumer relationships.
The competitive question for Nike is therefore straightforward:
Can Nike combine its global brand strength with products and experiences that feel sufficiently relevant to local consumers?
That will be more important than simply increasing advertising expenditure.
Why the Jordan Brand Still Matters to Nike Stock
Jordan remains one of Nike’s most valuable brand assets.
But its popularity creates a difficult balancing act.
Too much supply can reduce scarcity and encourage discounting. Too little supply can sacrifice near-term revenue.
Nike is currently prioritizing brand health over maximizing every possible short-term sale.
That could make the Jordan business temporarily weaker financially while management attempts to improve its long-term positioning.
Investors should watch whether future Jordan launches generate stronger demand at healthier prices.
The objective is not simply selling more pairs. It is improving the economic quality of the business.
Nike’s Biggest Problems and Challenges
Nike faces several major issues simultaneously:
- Weak overall revenue growth
- A prolonged decline in Greater China
- Pressure on Sportswear
- Weakness in the Jordan portfolio
- Intense competition from Adidas and other brands
- Growing competition from Chinese sportswear companies
- Digital distribution problems in China
- Heavy reliance on promotions in some markets
- Restructuring costs
- The need to restore product innovation and cultural relevance
The most important issue is that these problems are connected.
Weak products can lead to promotions. Promotions can weaken brand positioning. Lower demand can increase inventory. Inventory can then require further discounts.
Nike’s turnaround has to break that cycle.
What Is Nike Stock Actually Worth?
There is no single objectively correct value for Nike stock.
The answer depends heavily on assumptions about future revenue, margins, earnings and the speed of the turnaround.
Around October 2, market data showed NKE near $33 per share. Stock-analysis data showed a trailing P/E in the mid-teens and a forward P/E in the low-20s, although valuation figures can change rapidly as the stock and earnings estimates move.
This creates an important valuation issue.
Nike may appear inexpensive compared with its historical share price, but a lower stock price does not automatically mean the business is undervalued.
A stock can become cheaper because its expected earnings have fallen.
For Nike, valuation should therefore be considered alongside:
- Future revenue growth
- Gross-margin recovery
- Operating-margin improvement
- China stabilization
- Inventory quality
- Full-price selling
- Free cash flow
- EPS recovery
- Brand momentum
The strongest valuation signal would be evidence that earnings estimates are beginning to stabilize or rise.
What the Market Is Telling Us About Nike Stock
The October 2 reaction is particularly important.
Nike shares fell about 6% during the October 2 session after the company released its results and outlook.
The market response suggests that investors were more concerned about the deterioration in future revenue and earnings than reassured by the company’s improved gross margin.
That is a useful lesson when interpreting Nike stock updates:
Investors are currently focused on the quality and durability of the recovery, not merely on cost reductions.
If Nike eventually produces stronger revenue while maintaining improved margins, sentiment could change.
If revenue continues falling and the turnaround requires repeated restructuring, the market may continue to assign a lower valuation multiple.
source: fidelity.com
Nike Stock Outlook: What Investors Should Watch Next
The next several quarters are likely to be about execution rather than headlines.
Investors should watch these indicators closely:
1. Greater China revenue
A smaller decline would be an early sign that the market reset is beginning to stabilize.
2. North American growth
North America is currently providing some support. Sustained growth here would demonstrate that Nike can still generate demand in its largest market.
3. Sportswear and Jordan
These businesses need to move from being significant drags toward becoming contributors to growth.
4. Gross margin
The Q1 improvement to 42.8% is encouraging, but investors will want to know whether margins can remain healthy while Nike restores sales.
5. Digital sales
Nike Brand Digital fell 13% in Q1. A sustained recovery would provide evidence that Nike’s digital strategy is becoming more effective.
6. Inventory
Inventory declined 3% to $7.8 billion. Continued inventory discipline could reduce discounting and improve profitability.
7. Pace savings
Nike expects $2.5 billion of cumulative savings through fiscal 2031. Investors should monitor actual savings against restructuring costs.
8. Product innovation
This may ultimately be the most important factor.
Nike cannot cost-cut its way into long-term growth. It needs products consumers genuinely want.
Nike Stock Outlook 2026: Can Nike Recover?
Nike can potentially recover, but the latest evidence points to a recovery process that is still in an early and difficult phase.
The company retains substantial global scale, a powerful brand portfolio, a large performance business and significant financial resources.
But the latest numbers also show why investors remain cautious.
The company is forecasting another year of declining revenue. Greater China is still shrinking sharply. Sportswear and Jordan remain under pressure. And the new Pace restructuring program will take years to produce its expected savings.
The most important question is therefore not simply “Will Nike stock recover?”
It is:
Can Nike turn improved operational discipline and renewed product investment into sustained revenue growth and stronger earnings?
The next several earnings reports should provide increasingly useful evidence.
For now, the Nike investment outlook remains closely tied to execution in China, product innovation, brand health, margins and the company’s ability to turn its restructuring program into profitable growth.
Bottom Line
The latest Nike stock updates show a company in the middle of a substantial reset rather than a completed turnaround.
Fiscal Q1 2027 produced some encouraging operational improvements, particularly the 42.8% gross margin and continued momentum in performance sports. But those positives were outweighed by a 26% Greater China revenue decline and guidance for a high-single-digit revenue decline in fiscal 2027.
Pace could eventually lower Nike’s cost base and improve organizational efficiency, but the financial benefits are expected to take years.
For investors researching NKE, the most useful approach is to track the underlying business indicators rather than relying on the daily stock chart alone.
The clearest evidence of a durable Nike recovery would be a combination of stabilizing China sales, stronger product demand, healthier full-price selling, improving margins and a return to sustainable revenue growth.
Custom FAQ Section
What is the Nike stock price for 500 shares?
Using the October 2, 2026 closing price of approximately $33.02, 500 Nike shares would be worth about $16,510 before transaction costs and taxes. The market value changes whenever NKE shares move.
What is the latest Nike news today?
The major Nike news on October 2, 2026 is the market’s reaction to the company’s fiscal Q1 2027 earnings and new Pace restructuring program. Nike expects fiscal 2027 revenue to decline by a high-single-digit percentage and plans approximately $2.5 billion in cumulative savings through fiscal 2031.
Where can I see the Nike stock chart?
Nike trades under NKE on the NYSE. Investors can view the latest price, historical chart, trading volume and other market data through major financial-market platforms. Because prices change throughout the trading day, the exact quote should be checked at the time of viewing.
What are the latest Nike stock updates on Robinhood?
Robinhood’s NKE quote can show real-time, pre-market or after-hours information depending on the trading session and the platform’s display. The latest October 2 market data showed NKE around $33.02 at the session close.
Why is Nike stock falling?
The latest decline was driven primarily by concerns over Nike’s weak fiscal 2027 revenue outlook, a 26% decline in Greater China revenue and continuing weakness in Sportswear and Jordan. Nike also expects its turnaround and restructuring actions to create additional short-term pressure.
Can Nike stock recover?
Nike’s recovery depends on whether management can stabilize Greater China, improve Sportswear and Jordan, strengthen product innovation, maintain healthier margins and eventually return the company to sustainable revenue growth. The latest results provide both positive operational signals and significant evidence that the turnaround remains unfinished.
Is Nike stock a good investment?
That depends on an investor’s valuation assumptions, time horizon, risk tolerance and expectations for Nike’s recovery. The current business data show meaningful turnaround risks alongside potential recovery drivers, so investors should evaluate revenue trends, margins, China performance, cash flow and valuation rather than relying solely on the share price.
Also Read